



 Cinema Portal
 Election Portal
 Share Dhani Portal
 Unicode Page
 English Edition
 Share Training
 PREMIUM
 सुन-चाँदीको भाउ
 विदेशी विनिमयदर
 मिति रुपान्तरण
 पेट्रोलको भाउ
 तरकारी/फलफूल भाउ
 आर्थिक राशिफल
 आजको मौसम
 AQI Page



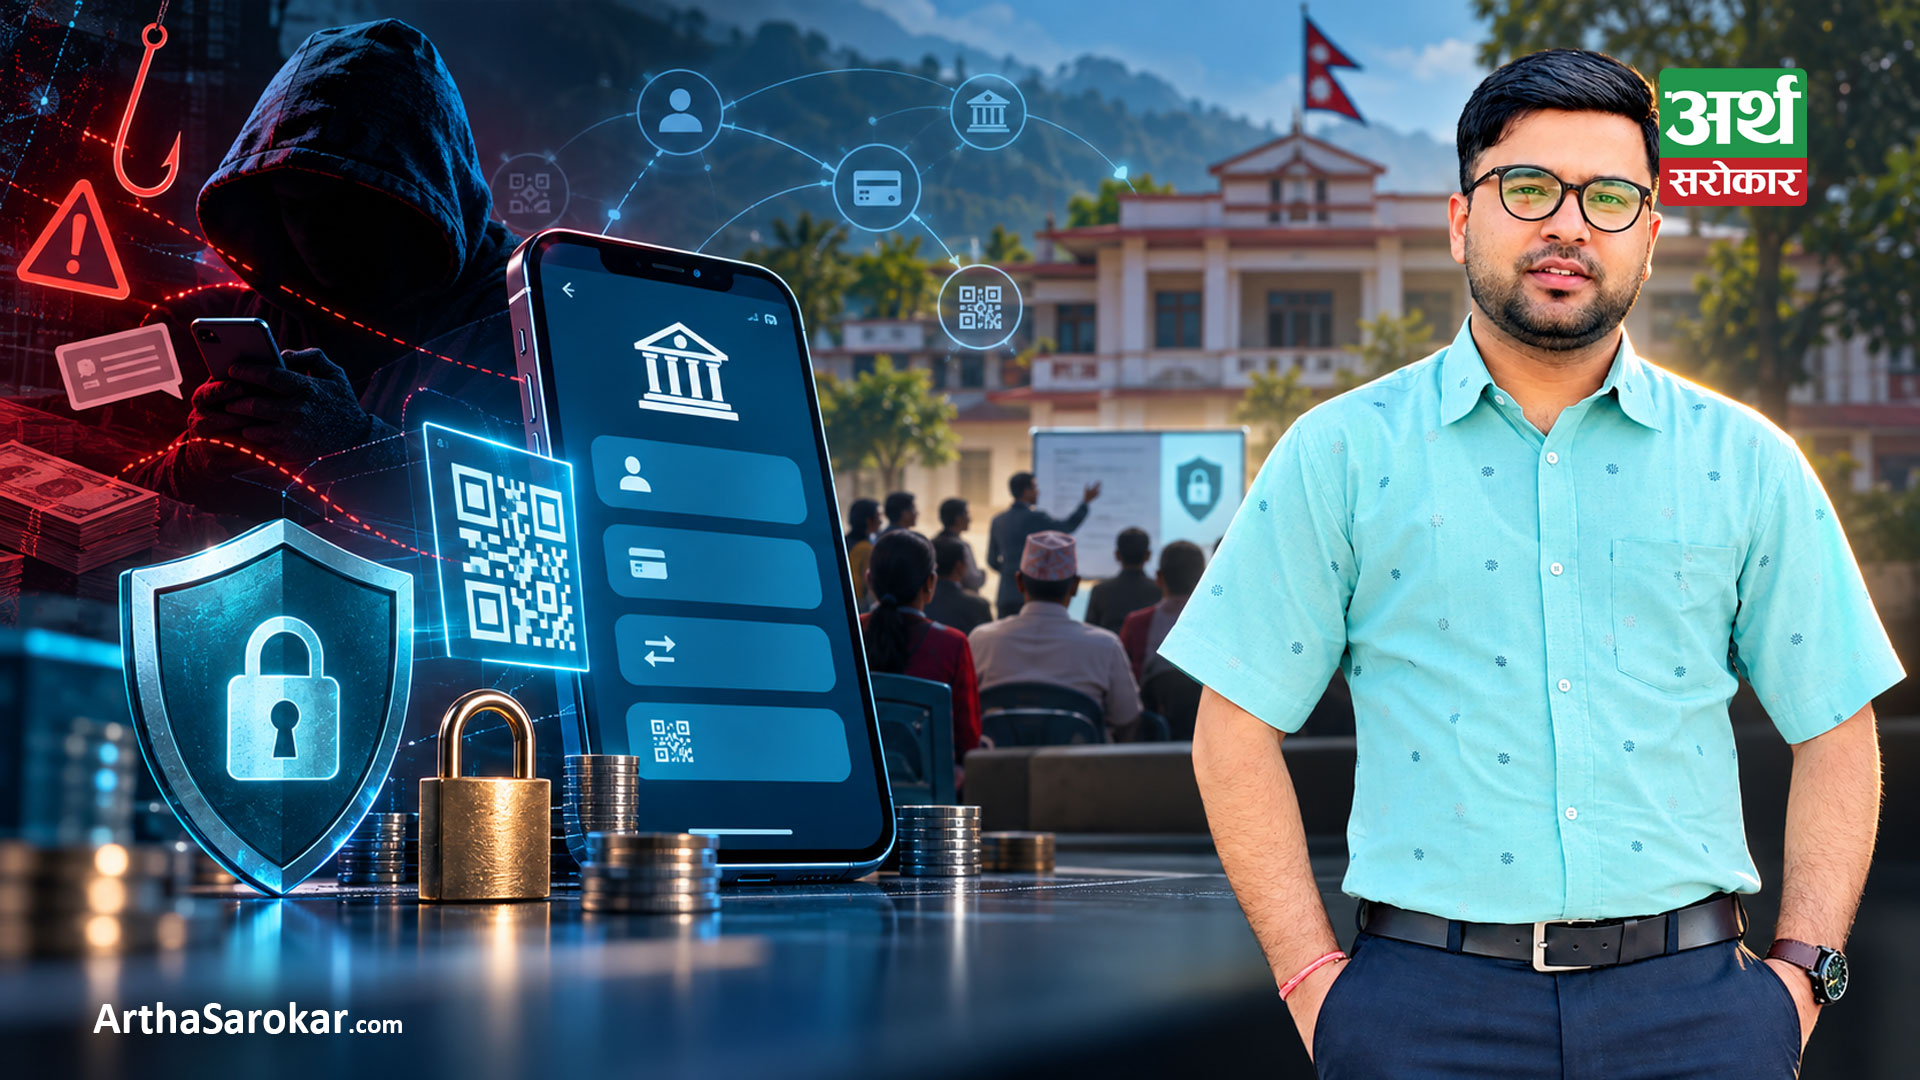
Kathmandu. Digital banking is a system of financial transactions done through mobile banking, internet banking, digital wallet, connect IPS, QR payment and other electronic means.
With the development of digital means for fast, easy and easy transactions, transactions through cheques and cash are decreasing significantly. But with its expansion, the risks of digital fraud, phishing, misuse of bank accounts and SIM cards, and digital payments have also increased.
How a person is cheated and how to avoid fraud is a personal matter, but what is the role of the local government in protecting and preventing this kind of fraud? Some time ago, I got a message through Messenger that I had to click on the link to get the property of my child, you have won a prize of Rs 25 lakh on Viber, I got a call to provide the bank account number in Nepal to get that prize. Even after that, I got a call from the bank to update the national identity card as per the information given by my friends and I got information that I had cheated about Rs 25 lakh by asking for OTP through the call.
There were many news reports in this regard, including: Phishing (use of fake linked website), OTP fraud (asking for code by posing as a bank employee), Money Mule (using account for the greed of commission), hundi (transferring money through informal means), investment scam (assuring unnatural profits) and cheating of various people.
No matter how careful we are, fraudsters are always trying to cheat. Is it possible only for banks and financial institutions, Nepal Rastra Bank and police administration to stop the increasing fraud through digital means? What role can the local government play to prevent such incidents?
Role to be played by local governments in preventing digital banking frauds
In Nepal, there is a system of rural municipality and municipal government at the local level. Which is as follows.
1. Village Municipality
2. Metropolitan Cities, Sub-Metropolitan Cities and Municipalities
Nagar & Rural Municipality Ward Committee
Each ward under a rural municipality or municipality has a ward committee. Also, there are various groups and organizations in the rural municipality and municipality, which are as follows.
a. Toll Development Agency, Toll Improvement Committee
b. Mothers’ Group, Women’s Self Help Group, Women’s Rights and Women’s Empowerment Group, Women Entrepreneur Group
c. Youth Clubs, Sports Clubs, Cultural and Social Youth Groups, Children’s Clubs and Student Groups
d. Farmers and Livestock Groups, Groups Affiliated with Agriculture and Livestock Cooperatives
e. Self Help Groups and Co-operative Societies, Other Co-operative Societies
f. Senior Citizens Group
G. Consumer Committee and Construction Committee
h. Local Businessmen and Entrepreneurs Group
With the initiative of the local government, awareness programs can be conducted to prevent digital banking fraud in all the wards and localities across the country by mobilizing the above-mentioned organizations, committees, clubs, and groups, and it can be expected that it will be very effective. The local level governments should coordinate and work on prevention, monitoring, investigation, protection of victims and public awareness to prevent incidents like bank account renting, money mule, hundi, fake websites, OTP frauds, and online investment inducements.
The main task of the local government should be to alert the citizens on time to prevent misuse of their accounts rather than arresting and investigating after the crime has been committed.
The work to be done by the local government (metropolitan city, sub-metropolitan city, municipality and rural municipality) is the main role of the local government as it is closest to the citizens, its main role is to create awareness, identify the initial risks and provide assistance to the citizens. For this, the following tasks should be done.
- Digital banking security campaign will be conducted in every ward level.
- To conduct regular online fraud and financial awareness programs through ward offices, schools, colleges, cooperatives and neighborhood development organizations.
- Provide practical training on how not to share OTP, PIN, password and bank account with others.
- To designate digital fraud assistance contact persons at ward level and to designate contact persons or help desks to help the fraudsters to lodge complaints with banks, police and related bodies.
This reduces the confusion of where to go and what evidence to take.
- To inform about the risks of misuse of bank accounts and SIM cards.
- Not to rent out a bank account for others in the temptation of giving money and to warn them of the risks and legal hassles that may arise from it.
- Teach that the money put by a stranger in the account should not be sent to another account on the basis of the advice of others, and that cash should not be withdrawn.
- Keeps a record of local digital fraud.
To conduct mandatory awareness programs targeting the elderly, students, people going for foreign employment and new users in digital banking.
To make digital literacy a mandatory priority in schools and communities.
To maintain the confidentiality of the complaints received, to maintain data on the types of fraud, affected groups and the means used. To review the risks every three months and revise the awareness campaign. To provide digital security contact persons in every ward, regular awareness programs, school-level training, and assistance in the complaint process to the citizens who have been cheated.
There is a need to create awareness about financial literacy and digital fraud control targeting different sections of the society (women, youth, farmers, senior citizens and businessmen). It provides measures to protect against cyber financial risks such as fake investment schemes, phishing links, fake bank employees, phone frauds in the name of relief and grants, and OTP/PIN theft by teaching safe savings, debt management and proper use of digital banking (mobile banking, QR payments). Students should be taught to recognize fake links, online gaming, betting, social media frauds, and fake voices or videos created by AI. Overall, financial literacy and awareness campaigns through various groups and organizations in coordination with local governments (metropolitan cities, sub-metropolitan cities, municipalities and rural municipalities) can enable the general public to conduct safe and conscious digital financial transactions through regular group meetings.
–Tulsi Ram Acharya’s article

प्रतिक्रिया दिनुहोस्